

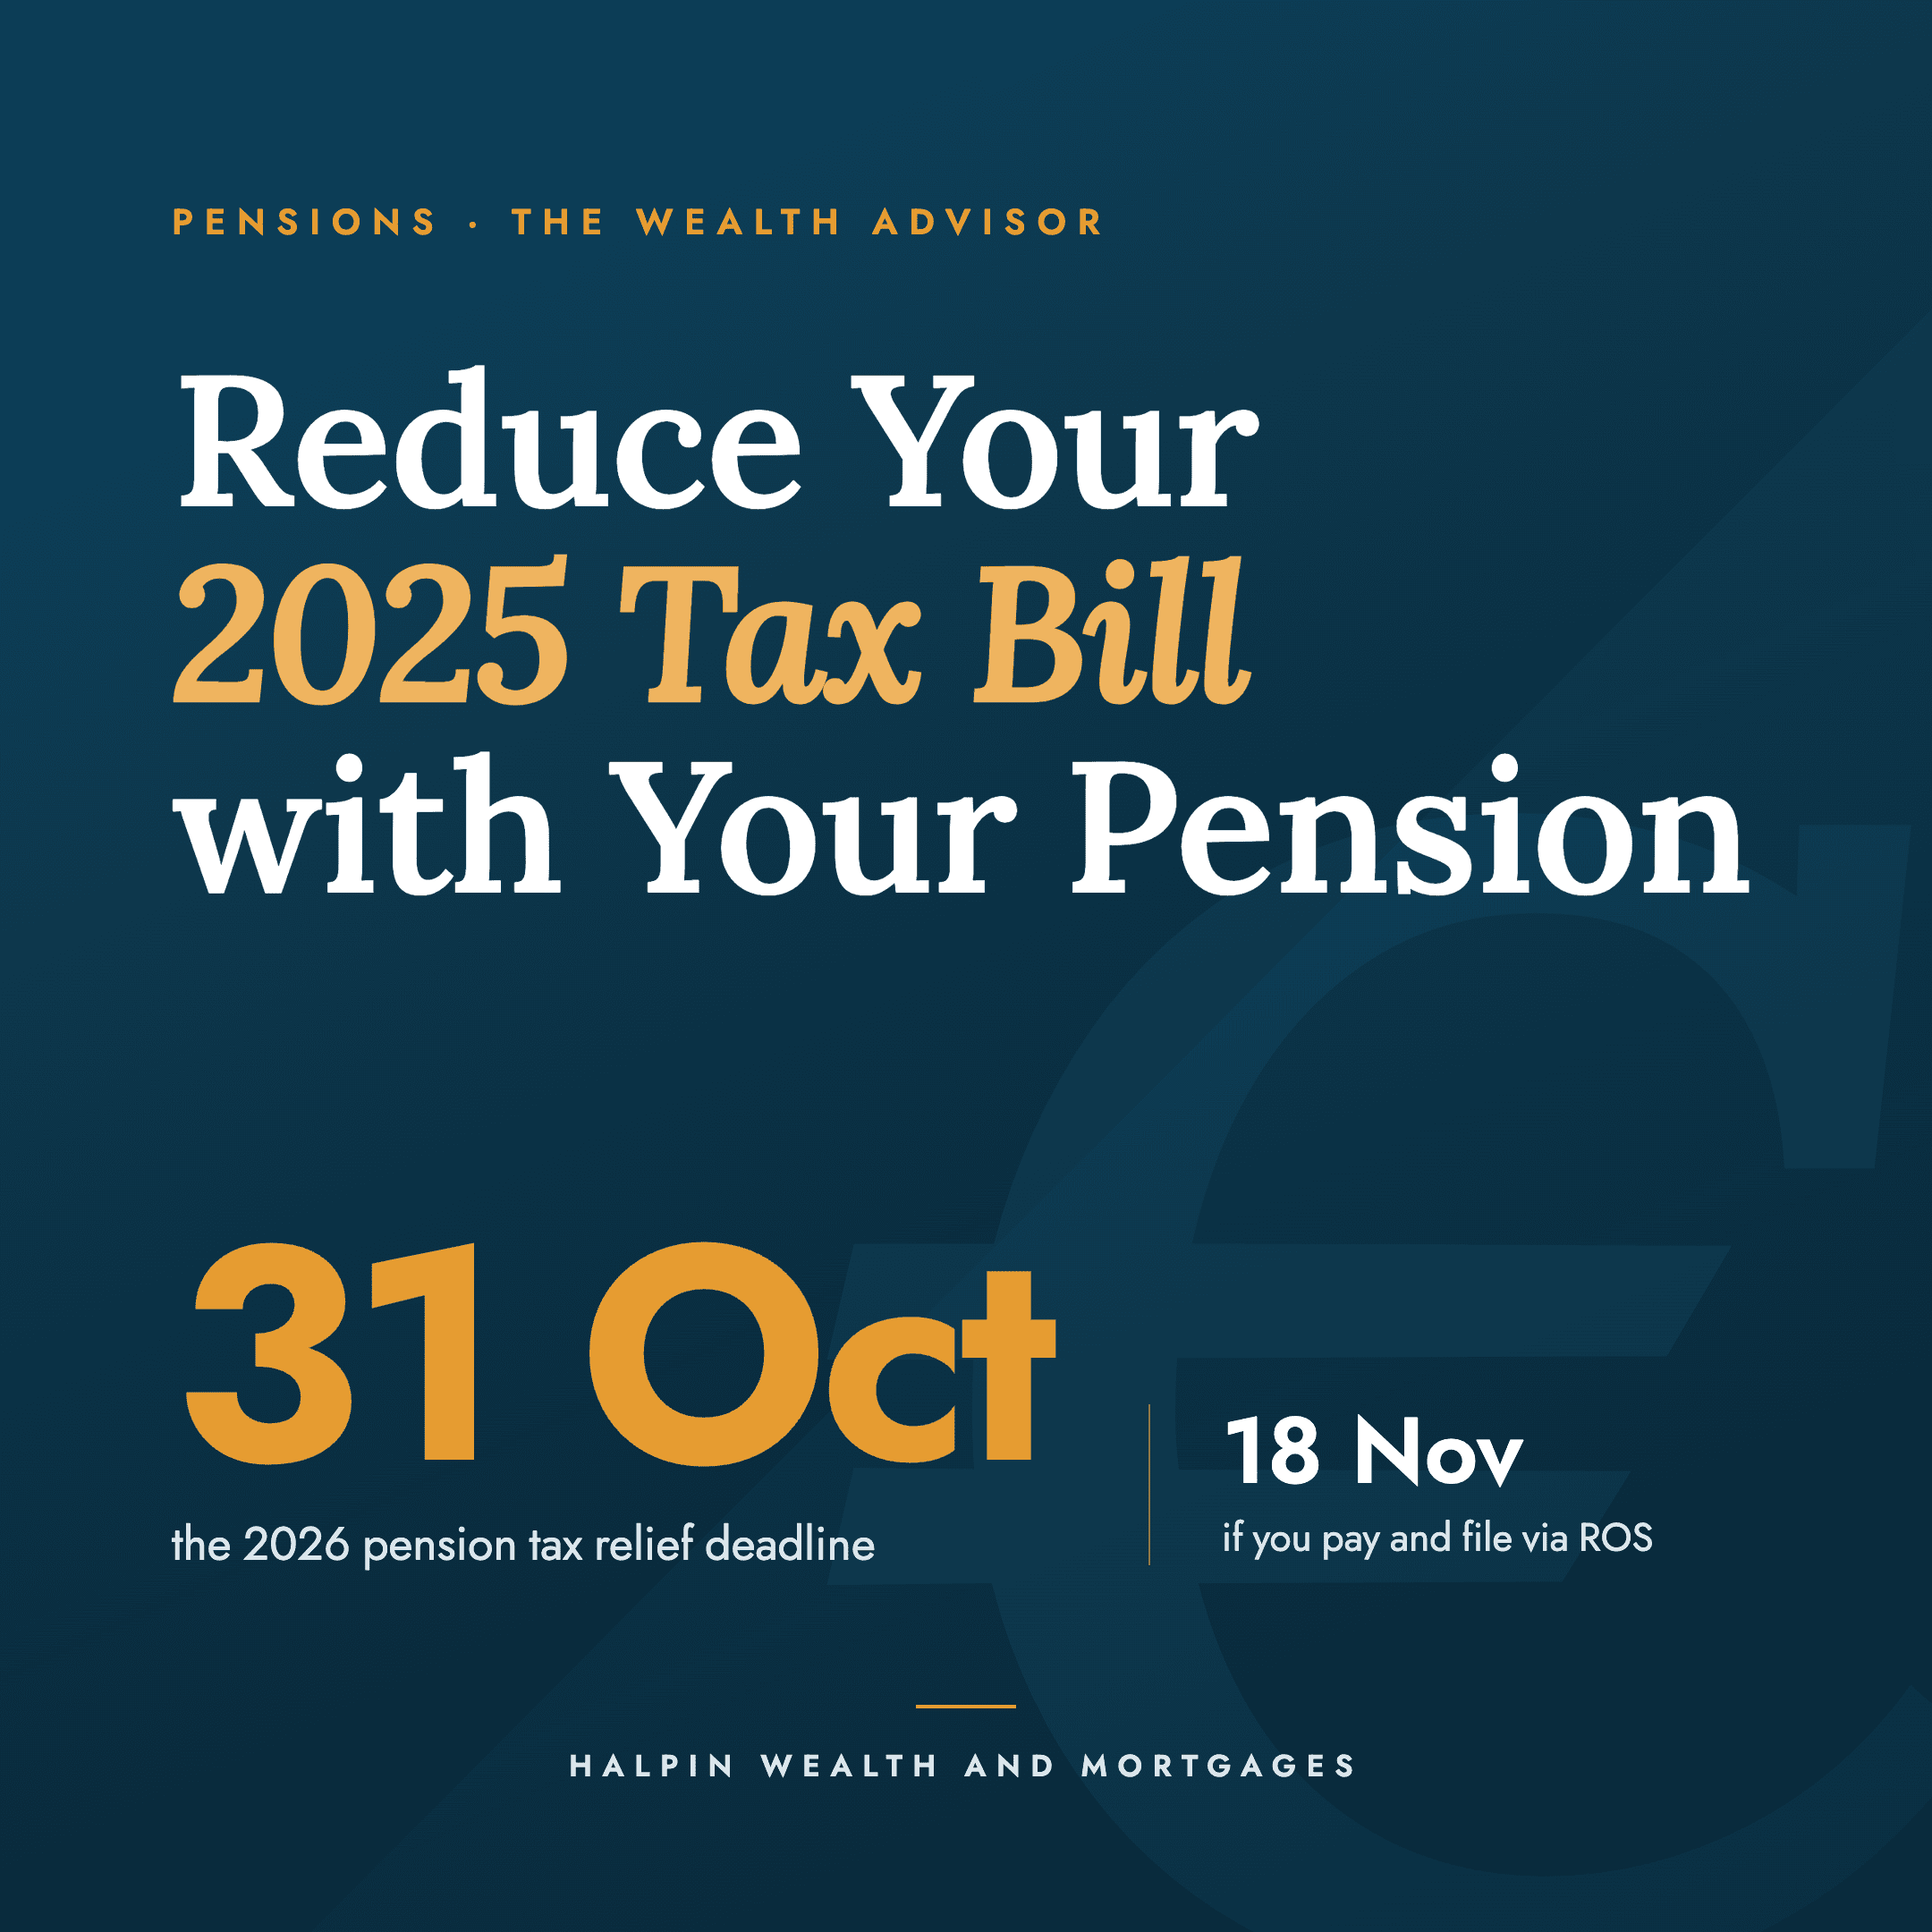
If you are looking at pension tax relief in Ireland for 2026, there is an important deadline to know about.
You may be able to make an additional pension contribution in 2026 and claim Income Tax relief against your 2025 income.
For many people, this can be a useful way to put more money towards retirement while also reducing their Income Tax bill.
Here is a simple explanation of how it works.
What is the pension tax deadline?
The standard deadline is 31 October 2026.
If you are eligible for the Revenue Online Service (ROS) extension and both pay and file online through ROS, the 2026 Pay and File deadline is 18 November 2026.
If you want to make a qualifying pension contribution and claim the tax relief against your 2025 income, the relevant contribution and claim must be made within the applicable deadline.
This is particularly relevant for people who are self-employed, company directors and others completing a self-assessment tax return.
How does pension tax relief work in Ireland?
When you make a qualifying personal pension contribution, you may be able to claim Income Tax relief on that contribution.
The relief is generally given at your marginal, or highest, rate of Income Tax, subject to Revenue’s limits.
For example:
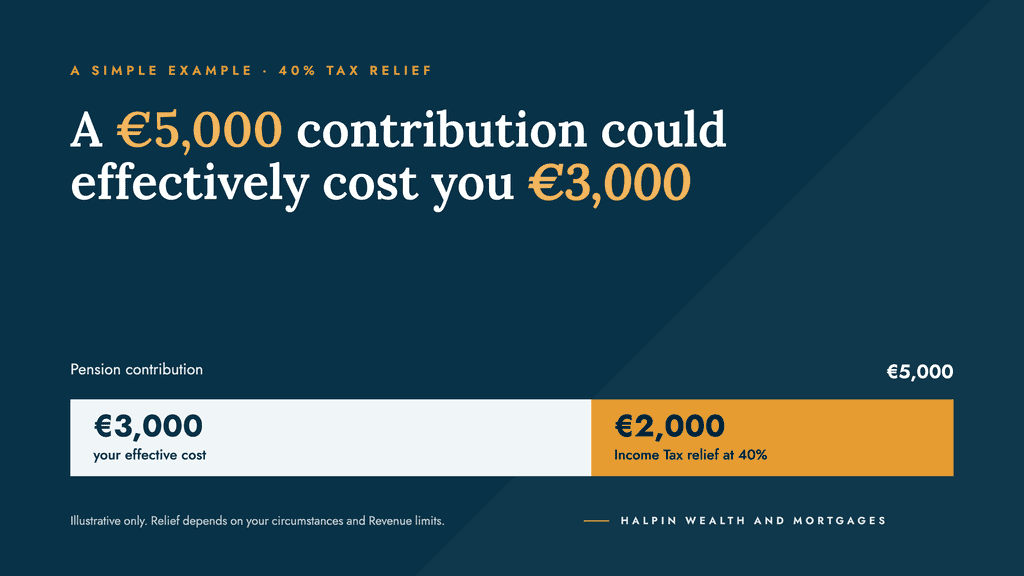
If you make a qualifying pension contribution of €5,000 and you qualify for Income Tax relief at 40%, the Income Tax relief could be €2,000.
This means the €5,000 pension contribution could effectively cost you €3,000 after Income Tax relief.
The exact amount of relief available will depend on your circumstances.
How much can you contribute and receive tax relief on?
Revenue sets limits based on your age and earnings.
| Your age | Maximum percentage of earnings eligible for tax relief |
| Under 30 | 15% |
| 30 to 39 | 20% |
| 40 to 49 | 25% |
| 50 to 54 | 30% |
| 55 to 59 | 35% |
| 60 or over | 40% |
There is also an annual earnings limit of €115,000 for the purpose of calculating tax relief.
A simple example
Imagine you are 42 and your relevant earnings for the year are €60,000.
The age-related limit for someone aged 40 to 49 is 25%.
25% of €60,000 = €15,000
This means up to €15,000 of qualifying pension contributions could potentially receive Income Tax relief for that year, subject to your circumstances and any pension contributions you have already made.
Why would you make an extra pension contribution?
There are two potential benefits.
1. You are putting more money towards your retirement.
Instead of leaving retirement planning until later, an additional contribution can help increase the amount invested for your future.
2. You may reduce your Income Tax bill.
If you qualify for pension tax relief, some of the cost of your contribution is effectively offset by the Income Tax relief available to you.
This is why the period before the tax deadline can be an important time to review your pension.
Does everyone get 40% tax relief?
No.
The amount of Income Tax relief available depends on your individual tax position.
Revenue states that qualifying pension contributions receive Income Tax relief at your marginal rate, subject to the relevant limits.
It is also important to know that employee pension contributions do not receive relief from USC or PRSI.
What if you already have a pension?
You may still be able to make an additional contribution.
For example, depending on your circumstances and pension arrangement, this could involve an Additional Voluntary Contribution (AVC) or an additional contribution to a PRSA or other qualifying pension product.
However, your existing contributions need to be taken into account when calculating how much additional contribution may qualify for tax relief.
What if you are self-employed?
This deadline can be particularly relevant if you are self-employed.
When completing your 2025 Income Tax Return in 2026, you may be able to make a qualifying pension contribution before the applicable deadline and elect to claim the relief against your 2025 income.
This can allow you to contribute towards your retirement while potentially reducing your 2025 Income Tax liability.
What should you do before the deadline?
If you are considering making an additional pension contribution, it is worth looking at it before the deadline rather than leaving it until the last few days.
You will need to know:
- what pension arrangements you already have
- how much you have already contributed
- your relevant earnings
- the tax relief available to you
- how much additional contribution may qualify for relief
- which deadline applies to you
At Halpin Wealth and Mortgages, we can help you understand your options and work out whether an additional pension contribution may be suitable for your circumstances.
Want to review your pension before the tax deadline?
Get in touch with the HWM team and we can talk you through your options in plain English.
Tax relief is subject to Revenue rules, individual circumstances and applicable limits. Pension and tax rules may change. The value of your investment can go down as well as up.